What Happens if I Drive a Rental Car Under 25
You can usually still rent and get coverage, but expect an extra daily fee and a closer look at what your own policy actually covers.

Being under 25 changes the cost, not the rental itself
- Young renter fee applies Most rental companies charge an extra daily fee for renters under 25. It's not a penalty for bad driving, it's just how they price the added risk, so budget for it before you book.
- Your policy may still follow you If you have your own car insurance, it often extends to a rental car the same way it covers your own car. Call your insurer before you travel and ask them to confirm it in plain terms for a rental under 25.
- Family policy terms vary If you're on a parent's policy, your coverage for a rental often depends on how the policy defines who's insured and for what. Ask specifically about rentals, not just about driving in general.
- Credit card rules differ by age Some credit cards offer rental coverage as a perk, but many exclude renters under 25 or cover less for them. Read the card's rental benefit terms before counting on it.
- Some cars may be restricted Rental companies sometimes restrict certain vehicle classes, like larger SUVs or specialty cars, for renters under 25. Ask at booking so you're not surprised at the counter.
Renting a car for a weekend trip out of state
A college student under 25 booked a compact car for a weekend trip to visit a friend at another school. At checkout, the rental counter added a young renter fee that wasn't shown during online booking, which caught them off guard since they'd budgeted tightly for the trip.
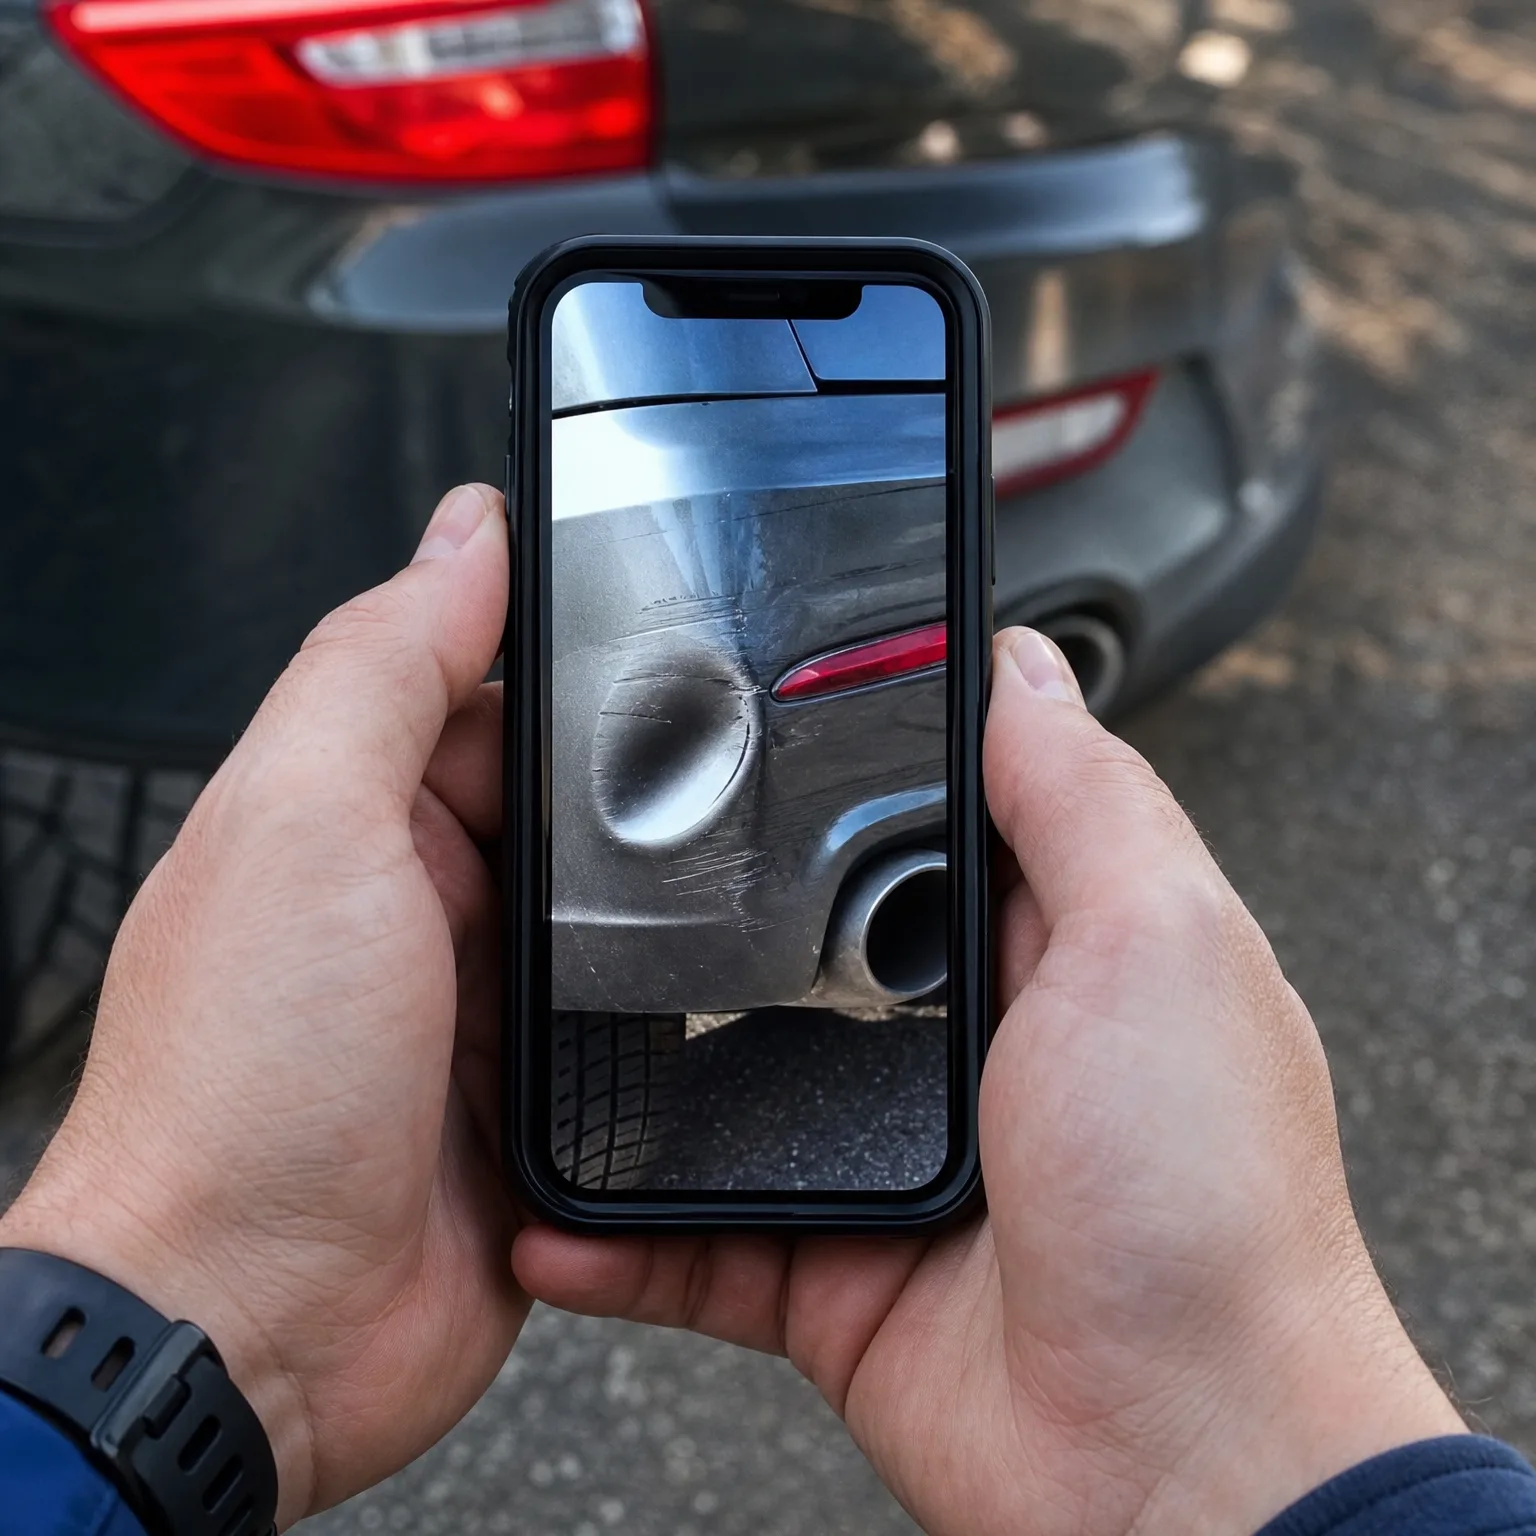
Before leaving campus, they'd called their parents' insurer to ask whether their coverage would extend to the rental. The agent confirmed it would, as long as the rental was for personal use and the trip matched what was listed on the policy. They also checked their credit card's benefits page and saw it excluded renters under 25, so they didn't rely on it. When a minor parking lot scrape happened during the trip, their own policy covered the repair, and the rental company's fee turned out to be the only real surprise of the trip.
Whether you call your insurer before renting
If you do
You find out exactly what's covered, what the young renter fee will be, and whether your card helps at all. If something happens during the rental, you already know who pays and how, so there's no scramble afterward.
If you don't
You're relying on assumptions about coverage that may not hold for a rental, especially if you're on a family policy. If a scrape or break-in happens, you could be stuck figuring out coverage after the fact, under pressure, from the rental counter.
Once you know how your coverage carries over, compare quotes to see if it beats paying for extra rental coverage.

Should I buy the rental company's insurance even if I'm covered?
It depends on how confident you are in your own coverage and how much risk you want to carry yourself. If your policy or card clearly covers the rental, buying the rental company's coverage on top is usually paying twice for the same protection.
But if you're not sure your coverage applies, or you're on a family policy with unclear rental language, the rental company's coverage can be a safer bet for a short trip. The real decision isn't about age, it's about certainty. If you can get a clear answer from your insurer before you book, you can skip the extra cost with confidence instead of guessing at the counter.
The fee for being under 25 is separate from your coverage, so paying it doesn't mean you're covered.